Market
Validate customer clusters, fleet commitments, competing capacity and the practicality of each gas-supply route.
We welcome discussions with funding partners who understand infrastructure development. Here we explain our proposed funding, assumptions and the matters we must resolve before commitment. These materials are for discussion and are not an investment offer.
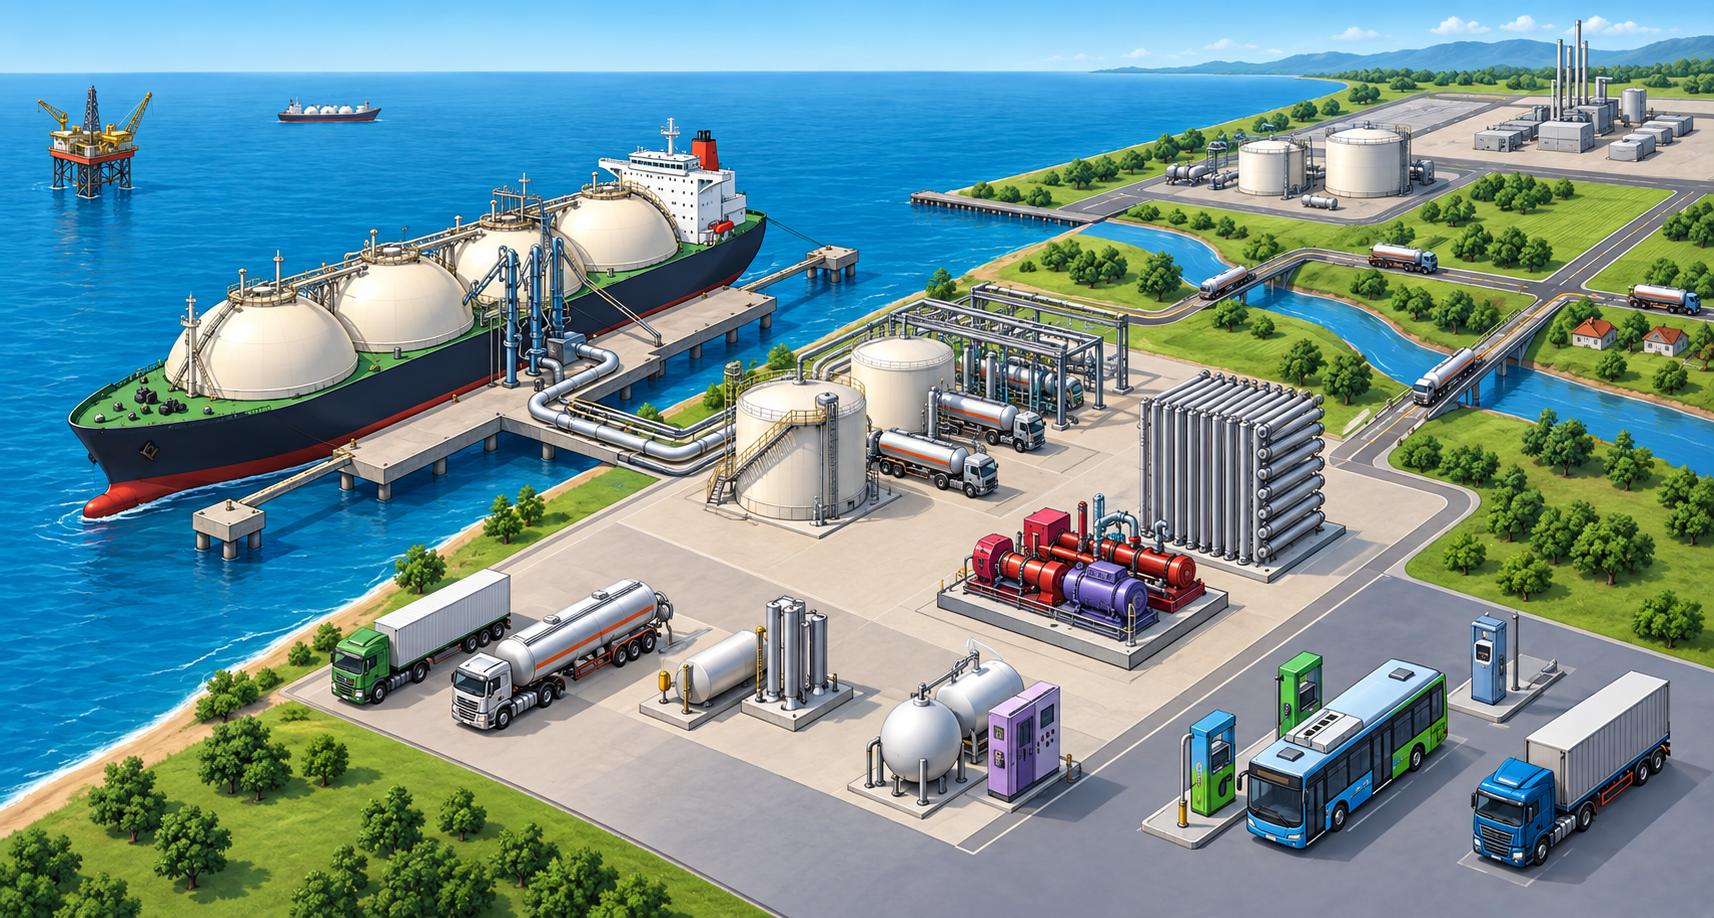
Explore how we could connect gas supply, storage, transport and customer facilities.
Explore our gas ecosystem ↗Select a year to review our Base Case forecast. This changes the display only; it does not change our assumptions or recalculate the model.
Projected revenue: ■ · Projected EBITDA: ■
| Operating assumptions | Medium station | High-capacity station |
|---|---|---|
| Initial module (m³/h) | 180 | 400 |
| Gross installed cost (USD) | 180,000 | 360,000 |
| Mature annual volume (scm) | 550,000 | 1,200,000 |
| Starting selling price (USD/scm) | 0.85 | 0.85 |
| Starting gas/logistics cost (USD/scm) | 0.52 | 0.52 |
USD price/cost escalation: 3% annually. Station OPEX: 12% of revenue; corporate/technology: 4%; maintenance: 2%; marketing: 2.5%. Operating calendar: 16 hours/day, 330 days/year. These are model assumptions.
Financial deployment starts with 180 m³/h medium and 400 m³/h high-capacity modules, expandable toward 1,100 and 2,400 m³/h. The larger reference packages below are not the initial installed capacities used by the model. The 500 m³/h options are outside the modelled 105/45 mix.
Our financial plan — references: Assumptions!B17:B39, K52:K53 · Unit Economics!B5:C17
We need to resolve several points before funding is committed. Our DSCR is 0.35x in Year 1, 1.05x in Year 2, 1.18x in Year 6 and 0.95x in Year 7, against our 1.35x target. Minimum unrestricted cash is US$2.384m, below our US$2.5m floor. Partner funding remains conditional. We must also resolve the US$7.38m accounting reserve, tax and site evidence, and the difference between three years of principal grace and the first repayment in December 2029.
Our ten-year project valuation gives an IRR of 35.75% and an NPV of US$47.08m at a 12% discount rate. These unlevered DCF estimates include a Year-10 terminal value of 7× EBITDA. We do not present them as seven-year cash returns or measures of lender repayment.
Our financial plan — references: Model Checks!A7:E21 · Assumptions!B8 · Debt Schedule!AK9 · DCF & Valuation!B30:B31
Validate customer clusters, fleet commitments, competing capacity and the practicality of each gas-supply route.
Connect site control, equipment scope, approvals, customer demand and a costed delivery plan before an investment decision.
Link funding commitments and drawdowns to milestones, verified evidence and defined commercial responsibilities. Assess equity, leasing, joint ventures, senior and subordinated debt as appropriate.
We are seeking funding; it is not yet committed. We have not set a minimum investor subscription in our financial plan.
We are seeking a US$100m financing ceiling. Our current plan allocates US$61.93m to bond funding and leaves US$38.07m unallocated. With US$9.05m of conditional partner contributions, our costed programme totals US$70.98m. We retain the alternative 60/10/30 structure for comparison; it is not our active funding case.
Planning terms: 6.5% coupon; preferred ten-year tenor; US$6.5m DSRA at close; 1.35x forward DSCR target. All terms remain subject to diligence and definitive agreements.
Our financial plan — references: Capital Stack!A18:D27, B40:B43
Our Base Case covers 2027–2033, including five years of station development. Figures are in USD millions unless stated otherwise. These are our planning forecasts, not audited results or guaranteed returns.
| Year | New stations | Cumulative stations | Projected revenue | Projected EBITDA | Net income | Operating cash flow | Debt service coverage (DSCR) |
|---|---|---|---|---|---|---|---|
| 2027 | 10 | 10 | 1.90 | 0.35 | -0.68 | 0.35 | 0.35× |
| 2028 | 20 | 30 | 10.07 | 1.85 | -0.04 | 1.80 | 1.05× |
| 2029 | 30 | 60 | 28.04 | 5.14 | 1.78 | 4.40 | 1.35× |
| 2030 | 40 | 100 | 54.92 | 10.06 | 4.78 | 8.05 | 1.35× |
| 2031 | 50 | 150 | 92.06 | 16.87 | 9.10 | 13.01 | 1.35× |
| 2032 | 0 | 150 | 110.12 | 20.18 | 11.50 | 15.25 | 1.18× |
| 2033 | 0 | 150 | 113.42 | 20.78 | 12.39 | 15.48 | 0.95× |
Our financial plan — references: Investment Summary!B17:H24 · Station Rollout!B5:H10